How to Prepare Your Asset Records for the Year-End Audit
Auditors want a register that matches your books and the assets on your premises. Here is how to reconcile, count, record disposals and get your asset records audit-ready, with a naira depreciation example and a manager's checklist.
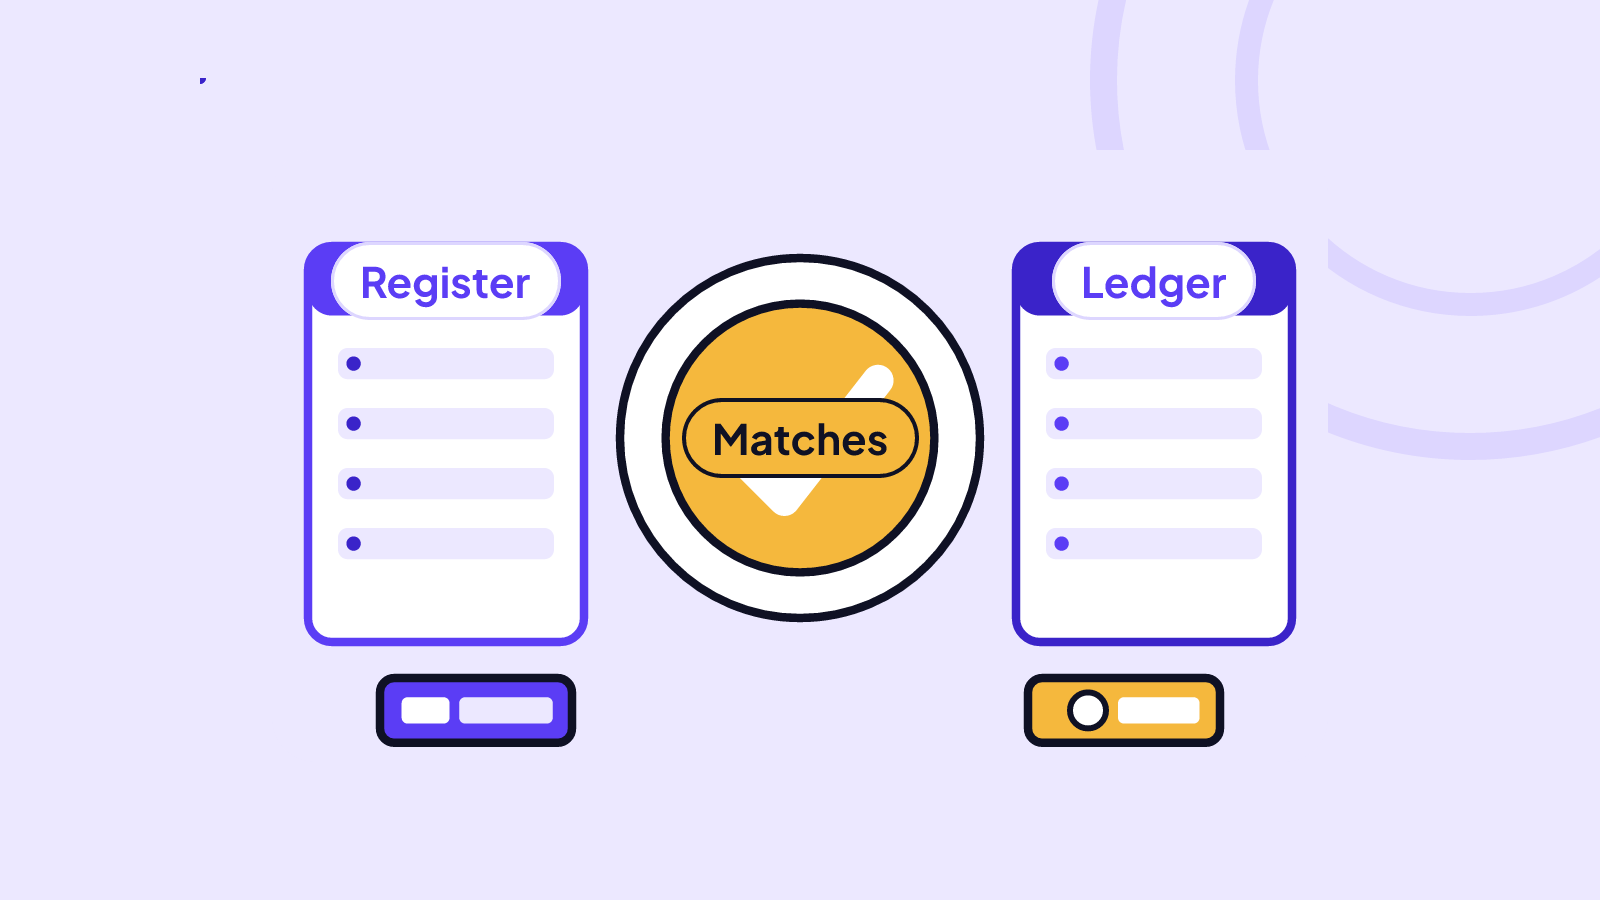
To prepare your asset records for a year-end audit, make sure three things agree: the fixed asset register, the accounting ledger and the assets physically on your premises. Count and tag what you own, record every purchase, disposal and write-off with proof, and calculate depreciation consistently. Auditors trust records they can trace to a document or a photo.
Key takeaways
- Auditors test three links: register to ledger, register to physical assets, and each asset to proof such as an invoice or photo.
- Start your clean-up weeks before the year-end, not in the week the auditors arrive.
- Every addition, transfer, disposal and write-off needs a date, a reason, an approver and a document.
- Depreciation should follow one stated method and life per asset class, applied the same way each year.
- A register kept all year round is far cheaper than one rebuilt under deadline.
What do auditors actually ask for?
A fixed asset register is the list of the long-lived items a business owns and uses, such as vehicles, generators, machines, computers and furniture, with what each cost and where it is. Auditors usually sample from it and ask three questions about each item:
- Does it exist? They pick items from the register and ask to see them, or pick items on the floor and look for them in the register.
- Is it yours and is the value right? They look for an invoice, receipt, delivery note or import document, and check the cost matches the ledger.
- Is the depreciation reasonable? Depreciation is the spreading of an asset's cost over the years it is expected to be useful, so each year's accounts carry a fair share of the cost.
If you can answer those three questions from the register itself, the audit goes faster and the follow-up queries are fewer.
How do you get the register ready, step by step?
1. Reconcile to the ledger. Total the cost column of the register by asset class and compare it with the fixed asset balances in your accounts. Differences usually come from a purchase booked as an expense, an item sold but never removed, or a typing slip. Fix each one or write down why it differs.
2. Do a physical count. Walk every site, office, store and workshop with the register in hand. Tick what you find, and list items found but not on the register as well as items on the register but not found. Nigerian businesses with several branches, or staff who work remotely, should include items held at homes and in vehicles.
3. Check the tags. An asset tag is a unique number or code, on a durable label or plate, fixed to an item and matched to its line in the register. Replace faded or missing tags, and make sure no two items share a number. A short, boring format such as ABJ-LAP-014 (site, type, running number) works better than anything clever.
4. Chase the proof. For every high-value item, attach the invoice or receipt and a photo showing the serial number. Where the original is lost, record what substitute you have, such as a bank transfer record or a supplier's reprint.
5. Settle the disposals. A disposal is any removal of an asset from the business, whether by sale, scrapping, donation, trade-in, theft or loss. Each one should be recorded with the date, the reason, the proceeds (if any) and who approved it. A write-off is the accounting entry that removes an asset's remaining value when it is scrapped or lost.
6. Review lives and methods. Check that each class still has a sensible useful life. If a generator you expected to last ten years is failing at six, tell your accountant now, not after the audit starts.
What does a worked depreciation example look like?
The simplest method is straight-line depreciation: the same amount is charged every year. The formula is (cost minus expected resale value at the end of its life) divided by useful life in years.
Say you buy a delivery van for ₦12,000,000, expect to use it for 5 years, and expect it to resell for ₦2,000,000.
- Yearly depreciation: (₦12,000,000 - ₦2,000,000) / 5 = ₦2,000,000
- After year 1: accumulated depreciation ₦2,000,000, so net book value (cost minus accumulated depreciation, what the books say it is worth) is ₦10,000,000.
- After year 2: accumulated depreciation ₦4,000,000, net book value ₦8,000,000.
Now suppose you sell the van at the end of year 2 for ₦9,000,000. Proceeds of ₦9,000,000 less net book value of ₦8,000,000 gives a gain on disposal of ₦1,000,000. Had it sold for ₦7,000,000, you would record a ₦1,000,000 loss. Either way, the register must show the sale date, the buyer and the proceeds, and the van must come off the list.
The figures are illustrative. Tax returns typically work from capital allowances, which are rates set under tax rules, rather than your book depreciation, so ask your accountant how the two relate for your business.
Who should own each step?
Audit trouble is rarely about maths. It is about nobody being responsible. A simple split works for most SMEs:
- Asset custodian (department head or branch manager): keeps the items in their area, reports moves, damage and loss.
- Admin or operations lead: tags new items, updates the register the same week something is bought, moved or sold.
- Finance manager: reconciles register to ledger monthly, calculates depreciation, approves disposals and write-offs.
- Owner or director: signs off write-offs above an agreed amount and reviews the count results.
Keep purchasing, recording and approving of disposals with different people where your team size allows, so no one person can both remove an asset and approve its removal.
What controls stop assets going missing?
Nigerian businesses face a familiar list of everyday risks: theft, power surges that kill equipment, flooding in the rains, market and warehouse fires, and road accidents involving company vehicles. Good records will not prevent these, but they let you see quickly what was affected and what remains.
- Check-out and return log for laptops, phones and tools issued to staff, signed by the person receiving them.
- Quarterly spot counts of a sample, with a full count at year-end.
- Transfer form whenever an item moves between sites or rooms.
- Exit checklist so staff return company items before final pay.
- Photos of each item, with the serial number visible, taken when it arrives.
- Rising replacement costs: a weaker naira has pushed up what many imported items cost to replace, so review values on the register at least yearly and flag items whose cost has moved sharply.
For the basics of building the list itself, see how to set up a fixed asset register for your business, and for the wider idea of tracking what you hold, what e-inventory is and why it matters.
How can VaultLog help with audit preparation?
VaultLog is VaultCova's asset register. You log each asset with its value, attach receipts and photos, and keep serial numbers alongside them, so the proof sits next to the item. Logging is free, and the Free Vault holds up to 30 assets.
A few features save real time before an audit:
- Schedule-of-assets export (PDF): download a branded register of all your assets, available on every plan.
- Grouped views by category and location: see what sits at each site, from the Individual plan up.
- Import from PDF, Excel or Word: attach an existing list in chat and Cova reads every asset into VaultLog, even from an untidy list (Pro and up).
- Receipt scanning: snap a receipt and Cova reads the purchase, then offers to add it to the vault (Pro and up).
- Value tracking and statements: follow how values change over time and download a statement for any period, grouped by location (Pro and up).
- Team members: Pro allows 3 seats and Business allows 5, so custodians and finance can work from the same register.
Year-end asset audit checklist
- Register totals agree with the ledger, by asset class
- Full physical count done at every site, differences listed
- Every item has a tag, and no tag is duplicated
- Invoice or receipt and a serial-number photo attached for high-value items
- All disposals, write-offs and thefts recorded with date, reason, proceeds and approval
- Police report or incident note filed for stolen items
- Transfers between sites updated
- Useful lives and depreciation method reviewed with your accountant
- Items issued to staff matched against the check-out log
- Fully depreciated items still in use, and idle items, flagged
- PDF copy of the register saved for the auditors
Frequently asked questions
How early should I start preparing asset records for an audit?
Aim to start four to six weeks before year-end, so the count and reconciliation are finished before the auditors arrive. If your register is updated monthly, the year-end work shrinks to a final count and a review.
What if I find assets that are not on the register?
Tag them, photograph them and add them with your best evidence of cost and purchase date. If there is no paperwork, record a reasoned estimate and note it as such, then agree the treatment with your accountant.
Do I need to count everything every year?
Most businesses count every fixed asset at least once a year, with extra spot checks on high-value or portable items such as laptops and phones. Your auditors may also sample and re-count on their own.
How do I record a stolen asset?
Record the date it was discovered, what was taken, its net book value and the police report reference. Then remove it from the active register with the write-off approved by a senior person.
A register is easiest to keep when you start small: open a vault and log your first few items in VaultLog today.