What is an Insurance Excess and How Does It Work?
The excess is the part of a claim you pay yourself before cover kicks in. Here is how it works in Nigeria, why it exists, and how to choose the right one.
Excess in plain terms
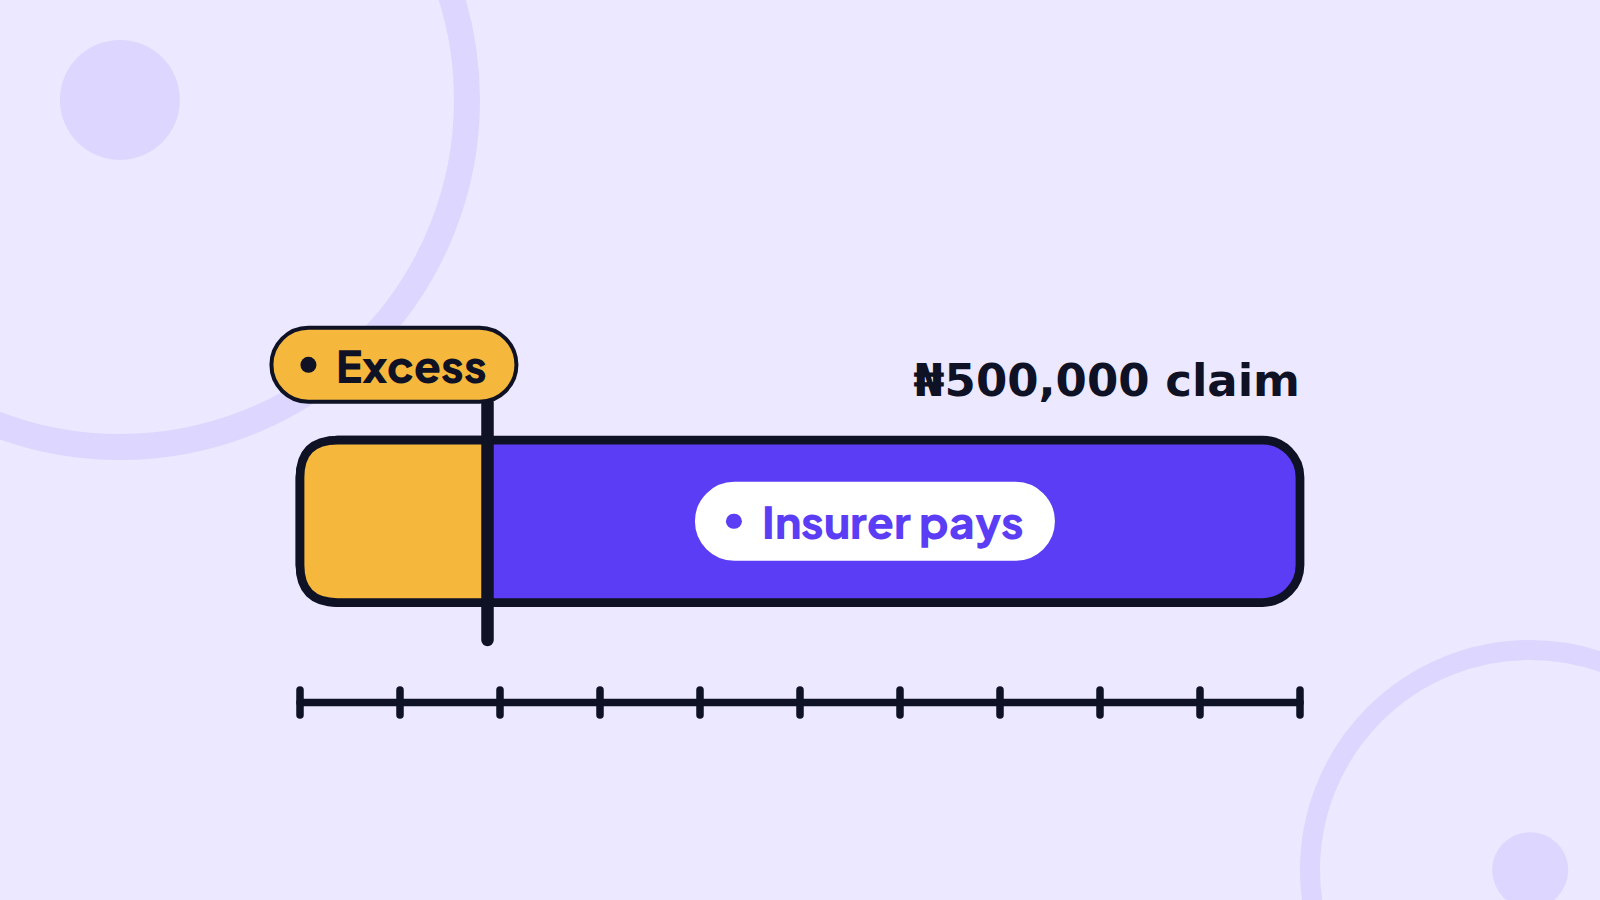
An excess is the amount you agree to pay out of your own pocket whenever you make a claim, before the rest of the payout comes from the underwriter. If your phone is stolen and it is valued at 400,000 naira, and your excess is 20,000 naira, the underwriter pays 380,000 naira and you cover the remaining 20,000 naira.
Most insurance policies carry some form of excess, though it varies by cover and underwriter. It is not a penalty and it is not a hidden fee. It is a standard part of how insurance works everywhere, including policies arranged through the licensed underwriters on VaultCova.
Why excess exists at all
Excess does two useful things.
- It keeps small, everyday costs off the underwriter's books, which keeps premiums lower for everyone. Without it, every scratch and minor loss would push premiums up.
- It keeps you invested in looking after what you own. If every single loss was paid in full with nothing from you, there would be less reason to be careful with your generator, your laptop, or your shop stock.
Think of it as the line between "small enough to absorb yourself" and "big enough to need real cover for."
How excess is usually set
Excess can be a flat amount or a percentage of the claim, depending on the item and the underwriter.
- Flat excess: a fixed naira amount, for example 10,000 naira on every claim under a gadget policy.
- Percentage excess: a percentage of the loss, common on higher value items or business stock, for example 5 percent of the claimed amount.
- Higher excess for higher risk items: things that are stolen often, like phones, sometimes carry a slightly higher excess than items that are rarely lost, like furniture.
Before you commit to cover, check your policy wording or quote for the excess that applies, so there are no surprises when you actually need to claim.
Excess and your premium: the trade-off
There is a direct relationship between excess and premium. A higher excess usually means a lower premium, because you are agreeing to carry more of the small risk yourself. A lower excess usually means a slightly higher premium, because the underwriter is taking on more of that small risk.
This is worth understanding when you look at a quote:
- A higher excess usually means a lower premium, so if you can comfortably absorb a bigger excess if something happens, that can work in your favour. The excess that applies is shown in the quote and policy wording.
- If you would rather have almost the full amount paid out with minimal cost to you at claim time, a lower excess usually costs a bit more upfront but gives you peace of mind.
Neither is wrong. It depends on your cash flow and how much risk you are comfortable holding yourself. This is different from cutting cover itself, which is not something to do carelessly. See how to lower your premium without cutting your cover for other ways to manage cost.
Excess is not the same as underinsurance
It is easy to confuse excess with the average clause, but they are separate things.
- Excess is a fixed amount or percentage you agree to pay on every claim, known in advance.
- The average clause is a reduction applied when the value you insured an item for is lower than its actual replacement value. It can shrink your entire payout, not just by a fixed amount.
You can read more about how underinsurance affects payouts in /resources/average-clause-underinsurance-payout-nigeria. Keeping your item values current is the best way to avoid that separate problem entirely.
A quick example to tie it together
Say you insure a generator worth 800,000 naira with a 5 percent excess. It gets damaged in a power surge and the repair or replacement cost comes to 500,000 naira.
- Excess amount: 5 percent of 500,000 naira, which is 25,000 naira.
- Underwriter pays: 475,000 naira.
- You pay: 25,000 naira.
If the generator had been insured for less than its real value, say 500,000 naira instead of 800,000 naira, the average clause could reduce the payout further, on top of the excess. That is why both figures, the value you declare and the excess in your policy terms, affect what you receive.
Getting the excess right for you
When you log an item on VaultCova and move to insure it, take a moment to check the excess in the policy terms. Ask yourself honestly what you could pay immediately if that item was lost or damaged tomorrow. That number is a good guide to how much excess you can comfortably carry.
Start a vault, log what you own with its current value, and when you are ready, talk to Cova about the cover that fits your budget. There is no pressure to insure everything at once, and you should check the policy terms for the excess before you buy.