House and home insurance in Nigeria
Householder's cover for your building and contents against fire, flood, storm and burglary. What it covers, what it costs, how much to insure for, and how to buy and claim.
House and home insurance in Nigeria is usually sold as a householder's policy. This one policy covers your building, your contents or both against fire, special perils such as flood and storm, and burglary. Owners insure the building and its contents. Tenants insure their contents. The premium is a percentage of the amounts you insure.
Key takeaways
- A householder's policy combines fire and special perils with burglary cover, for the building, its contents or both.
- Owners usually need buildings and contents cover. Tenants usually need contents cover only.
- Insure the building for its rebuild cost and the contents for their replacement value, or the average clause will reduce your claims.
- You can log your home for free, get a quote from Cova before you pay, and buy and claim in the chat.
What does householder's insurance cover?
Householder's insurance is a single policy for a home. It combines fire and special perils with burglary, and each appears as its own section. It can cover:
- Buildings: the structure and its fixed parts, such as the roof, walls, doors, built-in wardrobes, tiling, fence and gate
- Contents: furniture, appliances, electronics, clothes and household goods
The fire and special perils section covers fire, lightning and explosion, plus the special perils listed on your schedule: riot, strike and malicious damage, storm and flood, burst pipes, impact by vehicles or aircraft, bush fire and earthquake.
The burglary section covers theft involving forcible and violent entry into or exit from the home, and the damage done to the building during the break-in.
Phones, laptops and jewellery you carry outside the house need all risks cover, which protects an item against accidental loss or damage wherever you take it. This can be arranged separately for electronics and jewellery.
Do tenants and owners need different cover?
Yes. If you own your home, you usually insure the building and the contents. If you rent, the landlord usually insures the structure, so you only need cover for your own belongings. Read your tenancy agreement, because some make the tenant responsible for certain fittings. Insuring your belongings as a tenant explains the renter's side. Buildings vs contents insurance shows where the line falls between the two.
What is not covered?
Each section has its own usual exclusions. Your policy wording governs, but home insurance typically does not pay for:
- Theft without forced entry, including theft by members of the household unless entry was forced
- Property left in the open, and cash
- Wear and tear, gradual deterioration and damage caused by poor maintenance
- Losses while the home is left empty for longer than the wording allows
- Consequential loss unless added, and war and nuclear risks
The policy also comes with conditions. Keep the home secured with the locks or burglar-proofing the wording asks for, and tell the underwriter if the way you use the home changes.
How is home insurance priced?
The premium is a rate multiplied by the sum insured, which is the amount you declare and the most the policy will pay. The rate depends on the underwriter, the location, how the building is constructed, how it is secured, and how exposed it is to risks such as flooding.
As an illustration, at a householder's rate of 0.95% a year:
- An owner insuring a building with a ₦30,000,000 rebuild cost and ₦6,000,000 of contents insures ₦36,000,000 in total. The premium is ₦36,000,000 x 0.95% = ₦342,000 a year.
- A tenant insuring ₦4,000,000 of contents pays ₦4,000,000 x 0.95% = ₦38,000 a year.
Cova quotes your exact figure before you pay. On the Individual Vault and above, putting several assets into one policy can save up to 6%. Any item with no photo or receipt on file is priced 10% higher.
How much should you insure for?
Insure the building for its rebuild cost, meaning what it would cost to clear the site and build it again today. This is not its market price, because the market price includes the land. Insure contents at replacement value: what each item would cost new today.
If you insure for too little, many policies apply the average clause, which pays only the same share of a loss as your sum insured is of the true value. For example, a house that costs ₦30,000,000 to rebuild but is insured for ₦20,000,000 is covered for two thirds of its value. A ₦6,000,000 fire loss then pays ₦6,000,000 x (₦20,000,000 ÷ ₦30,000,000) = ₦4,000,000, less the excess. The excess is the first part of each claim, which you pay yourself.
To get contents right, our household inventory checklist takes you through the home room by room.
How do you buy and claim through VaultCova?
VaultCova is not an insurer. Licensed underwriters provide the cover and carry the risk.
To buy:
- Log your home and contents in VaultLog for free, with photos and receipts.
- Ask Cova for a householder's quote. Cova shows the cover and its price before you pay.
- Pay by card, bank transfer or from your wallet. Your policy and certificate are issued, and most cover is bound instantly.
To claim:
- For a burglary, report to the police straight away and get a police report. For a fire, keep the fire service report if they were called.
- Photograph the damage, keep damaged items for inspection, and file the claim in the chat with Cova or from Claims.
- Claim while the policy period is still running. A loss cannot be claimed once the cover has ended.
How to file an insurance claim covers each step in more detail.
Frequently asked questions
How much does home insurance cost?
The premium is a percentage of the value you insure, so it grows with your home and contents. As an illustration, at 0.95% a year, ₦4,000,000 of contents costs ₦38,000. The exact figure depends on the underwriter, the location and the risk, and Cova quotes it before you pay.
What does home insurance cover?
A householder's policy covers fire and special perils, such as lightning, flood, storm and riot, plus burglary with forced entry, for your building, contents or both. Portable valuables away from home need separate all risks cover.
What documents do I need to buy home insurance or make a claim?
To buy cover, you log your home in VaultLog, get a quote from Cova and pay. To claim, you need proof of ownership and value, such as receipts, photos and serial numbers, plus a police report for any theft and a fire service report where the fire service was called.
How are home insurance claims paid?
The payout follows your policy wording. If you are underinsured, the average clause reduces the claim, and then the excess is deducted. A settled claim is paid into your wallet, and you can withdraw it to a bank account in your own name.
Can I cancel my home insurance if I change my mind?
Yes. Within 14 days of the cover starting, you can cancel and get a pro-rata refund for the unused days. After that, our team can still cancel it for you. Cancellation is not offered for cover that has a claim on it.
Do I have to insure everything at once?
No. Log everything for free to see your full exposure, then insure what you choose, when you are ready. You can add more items to your cover later.
Start a free vault, log your home and contents, and ask Cova for a quote when you are ready.
Cover it in minutes, not days
Log what you own, get the cover that fits you from licensed underwriters, and pay in the app.
Insure my homeRead next
All resources
What Happens to Your Insurance Cover When You Move House in Nigeria?
Moving is one of the riskiest moments for your belongings, and your cover may not follow you automatically. Learn what to tell your underwriter, how to protect items in transit, and how to update your vault.
Insuring Your Home While You Travel or Work Away
Leaving home empty can affect your cover. Learn how unoccupied-home rules usually work, what to tell your underwriter and what to do before you go.
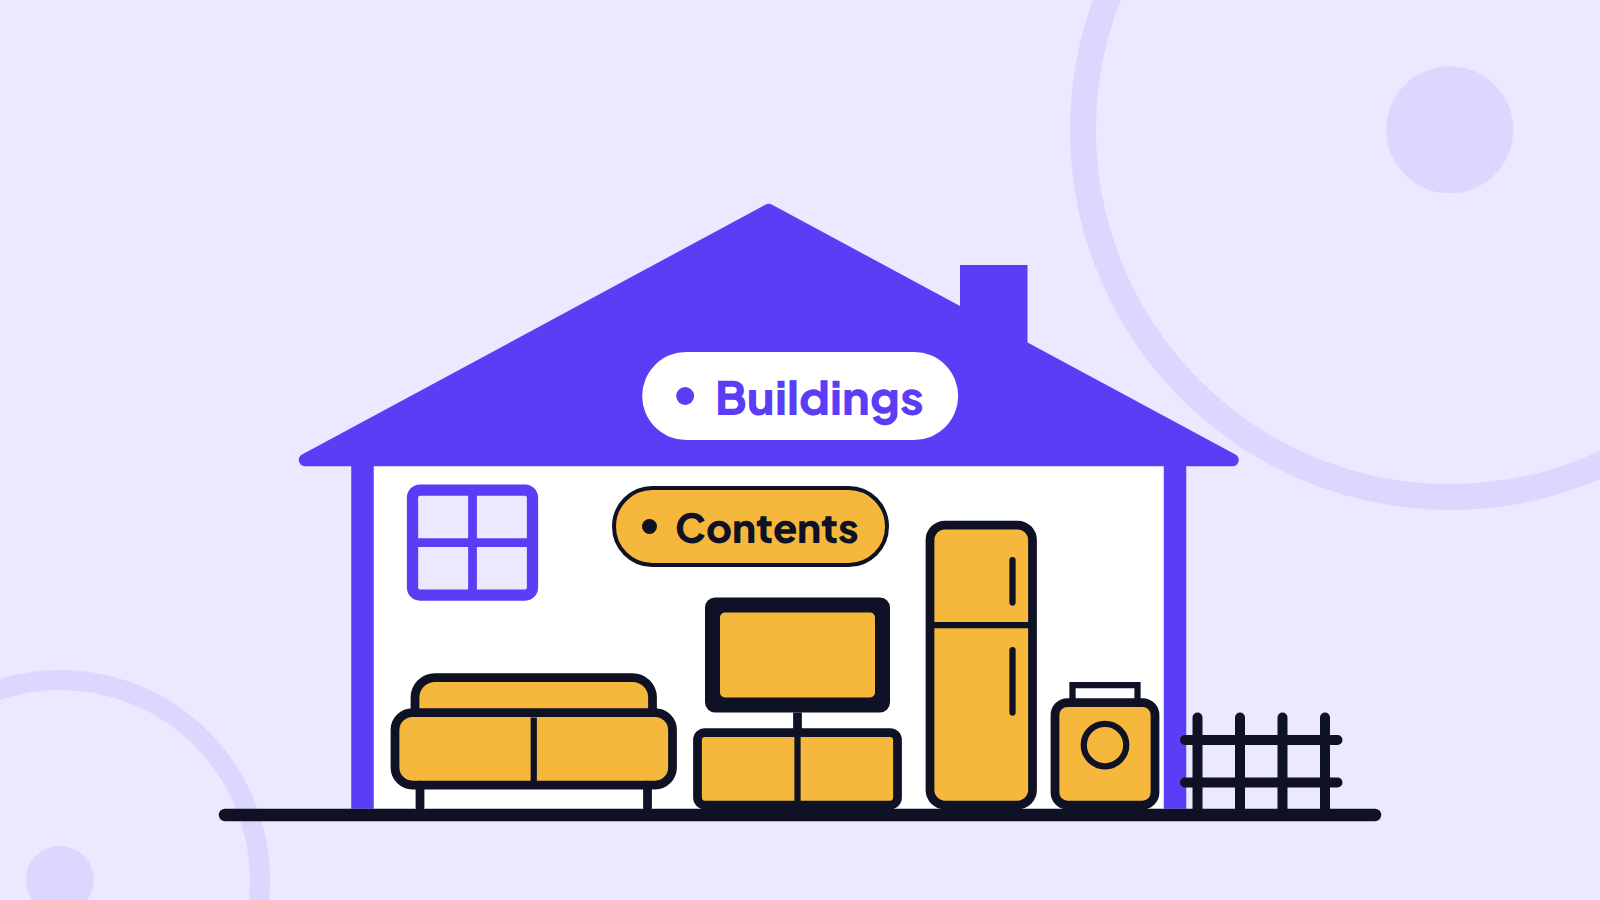
Buildings vs Contents Insurance: What Is the Difference?
Many Nigerians assume one policy covers everything about their home. Here is the real difference between buildings and contents insurance, and why you may need both.