Guides
Step-by-step how-tos for logging, valuing and insuring what you own.
Fire Safety at Home and Work: Gas, Generators and Wiring
Gas cylinders, generators and wiring are three common fire starters you can control. Learn the simple placement, storage and checking habits that cut the risk at home and in a shop or office.
How to Prepare Your Asset Records for the Year-End Audit
Auditors want a register that matches your books and the assets on your premises. Here is how to reconcile, count, record disposals and get your asset records audit-ready, with a naira depreciation example and a manager's checklist.
HMO vs Personal Accident Insurance: What Is the Difference?
An HMO plan pays for your healthcare at network hospitals, while personal accident insurance pays set benefits after an accident. Learn what each covers, where they overlap and when you may need both.
Disclosure in Insurance: What You Must Tell Your Insurer
Disclosure means telling your insurer every fact that could affect their decision to cover you or what they charge. Learn what counts as material, how proposal forms work and what happens if you leave something out.
Best Car Insurance: Why You Need More Than Third Party
The best car insurance is the cover that repairs or replaces your own vehicle, not just the legal minimum. See what third-party leaves out and how to choose between comprehensive and Autobase plans.
Personal Accident Insurance: Benefits and Where to Get It
Personal accident insurance pays set benefits if an accident causes death, disability or medical bills. Learn what it covers, what it excludes, how to claim, and how to choose where to buy it.
Group Life Insurance for Employers: How It Works and What to Do
Group life insurance pays a lump sum to the family of an employee who dies while on your scheme. Learn how the sum is set, what medical evidence does, and how joiners and claims work.
What an Insurance Risk Survey Looks At and How to Act on It
A risk survey is an underwriter's inspection of your premises. Learn what surveyors check, how their recommendations affect pricing and claims, and how to close each one out with proof.
How to Set Up a Fixed Asset Register for Your Business
A fixed asset register lists what your business owns, what it cost, where it is and what it is worth now. Here is how to set one up, who should own each step, and a checklist.
Business Interruption Insurance in Nigeria: Cover and Indemnity Period
How business interruption insurance pays lost gross profit after a fire, how the indemnity period and sum insured work, and a worked naira claim example.
Why Insurance Claims Get Reduced or Refused in Nigeria (and the Fix)
Most reduced or refused claims come down to a handful of avoidable causes: underinsurance, broken policy conditions, excluded events, incomplete disclosure and missing proof. Here is how each one works and how to avoid it.
Power Surges in Nigeria: How to Protect Your Electronics and What Insurance May Cover
Unstable power and generator switchovers can quietly destroy TVs, fridges and laptops. Learn how to reduce the risk, what insurance may cover, and how to prepare so a claim goes smoothly.
Insuring a Small Shop in Nigeria: Fire, Theft and Stock in One Policy
A small shop faces fire, break-ins, power surges and flooding every season. Here is how to combine stock, fittings, equipment and cash into one sensible policy, and how to avoid being underinsured.
What to Do in the First Hour After a Burglary in Nigeria
A burglary is stressful, and what you do in the first hour affects your safety, the police investigation and any insurance claim. Here is a calm, practical checklist for Nigerian homes and shops.
How to Lower Your Insurance Premium in Nigeria Without Cutting Your Cover
Want to pay less for insurance without leaving gaps? Here are practical ways Nigerians can reduce premiums, from choosing the right excess to improving security, while keeping enough cover to be paid in full.
Marine Hull Insurance vs P&I: What Is the Difference?
If you own or run a vessel in Nigeria, hull cover and P&I cover solve different problems. Here is a plain explanation of what each one actually protects.
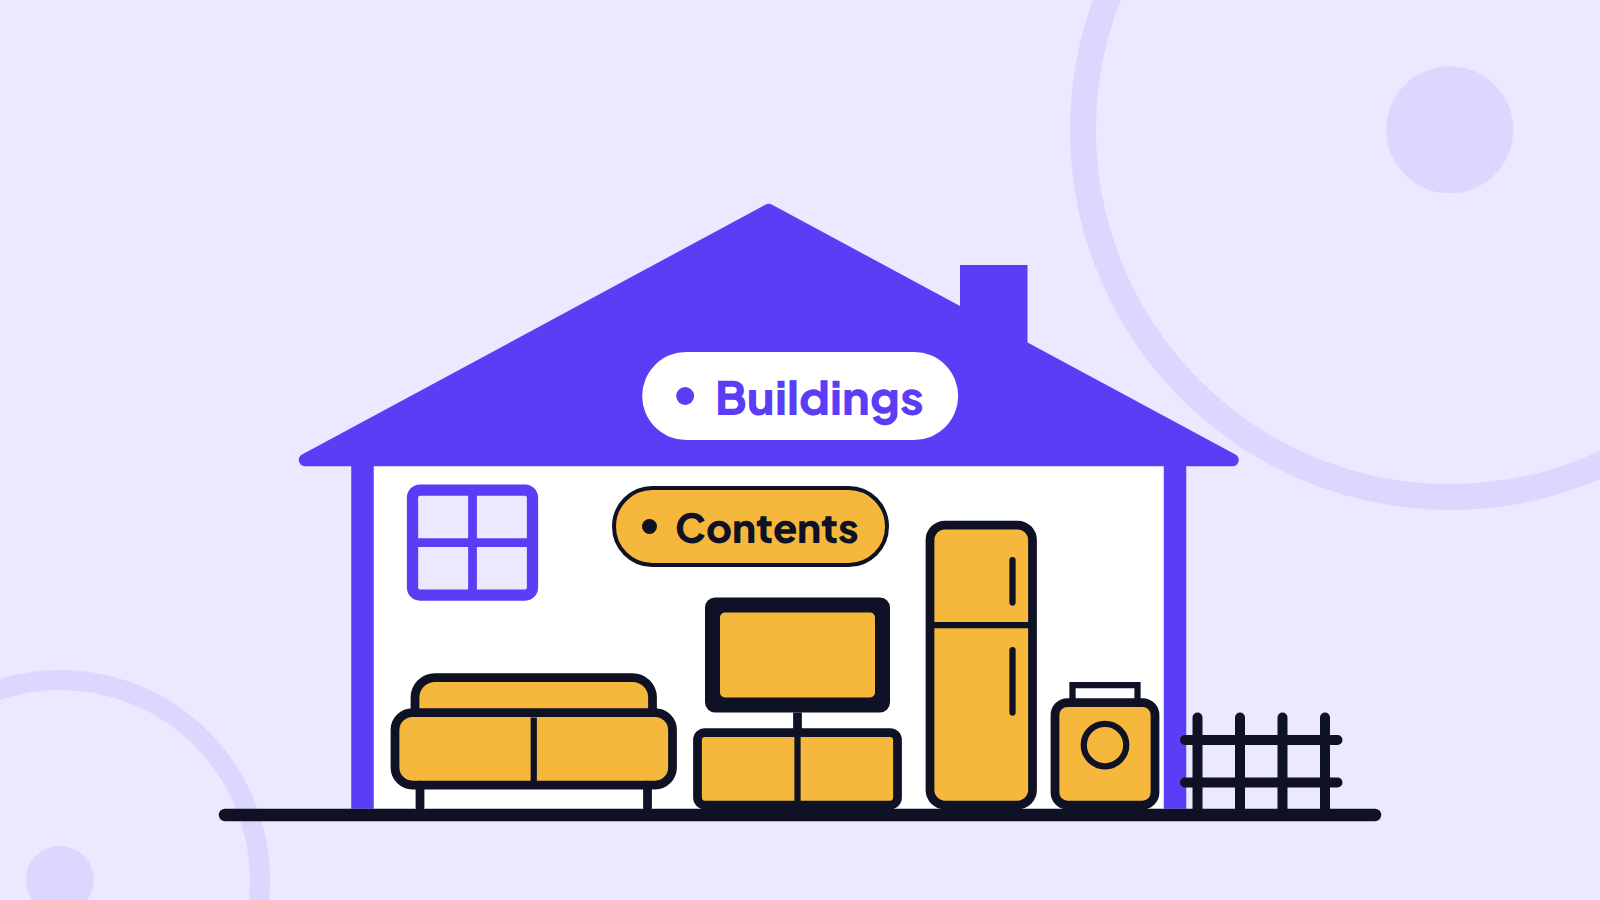
Buildings vs Contents Insurance: What Is the Difference?
Many Nigerians assume one policy covers everything about their home. Here is the real difference between buildings and contents insurance, and why you may need both.
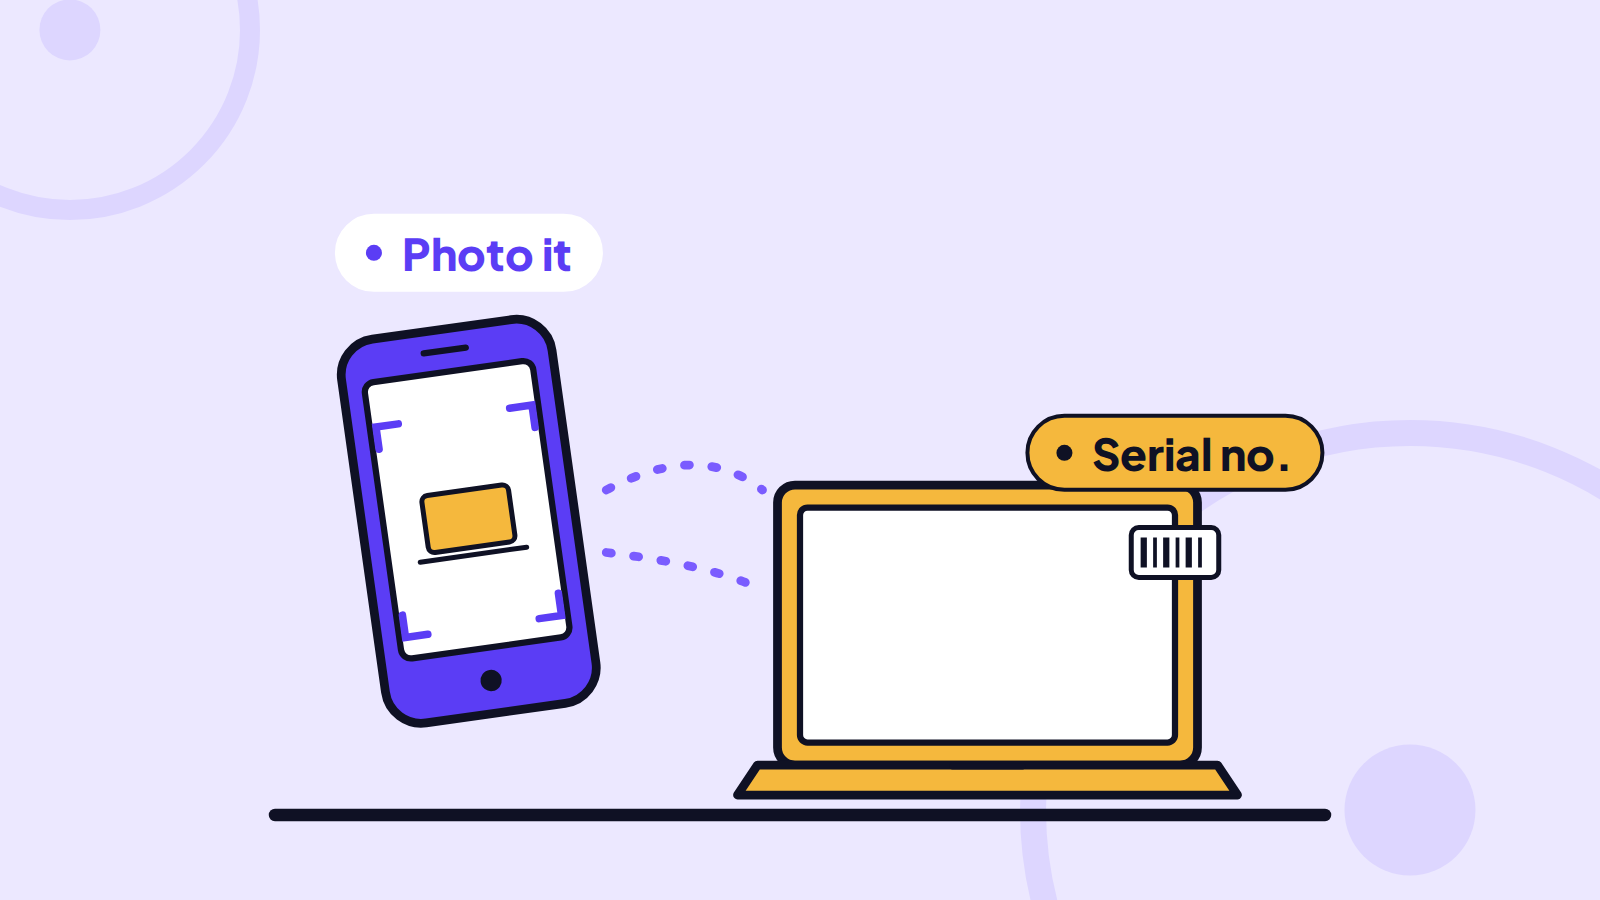
How to Prove Ownership and Value for an Insurance Claim
Receipts, photos, serial numbers, valuations and what to do when the receipt is gone: how to gather proof an insurer accepts, where to keep it, and what an adjuster will ask for.
How to Insure Your Business Stock and Inventory in Nigeria
A practical guide for shop owners, traders and small manufacturers on insuring stock and inventory against fire, theft and flood, and getting a fair payout when it matters.
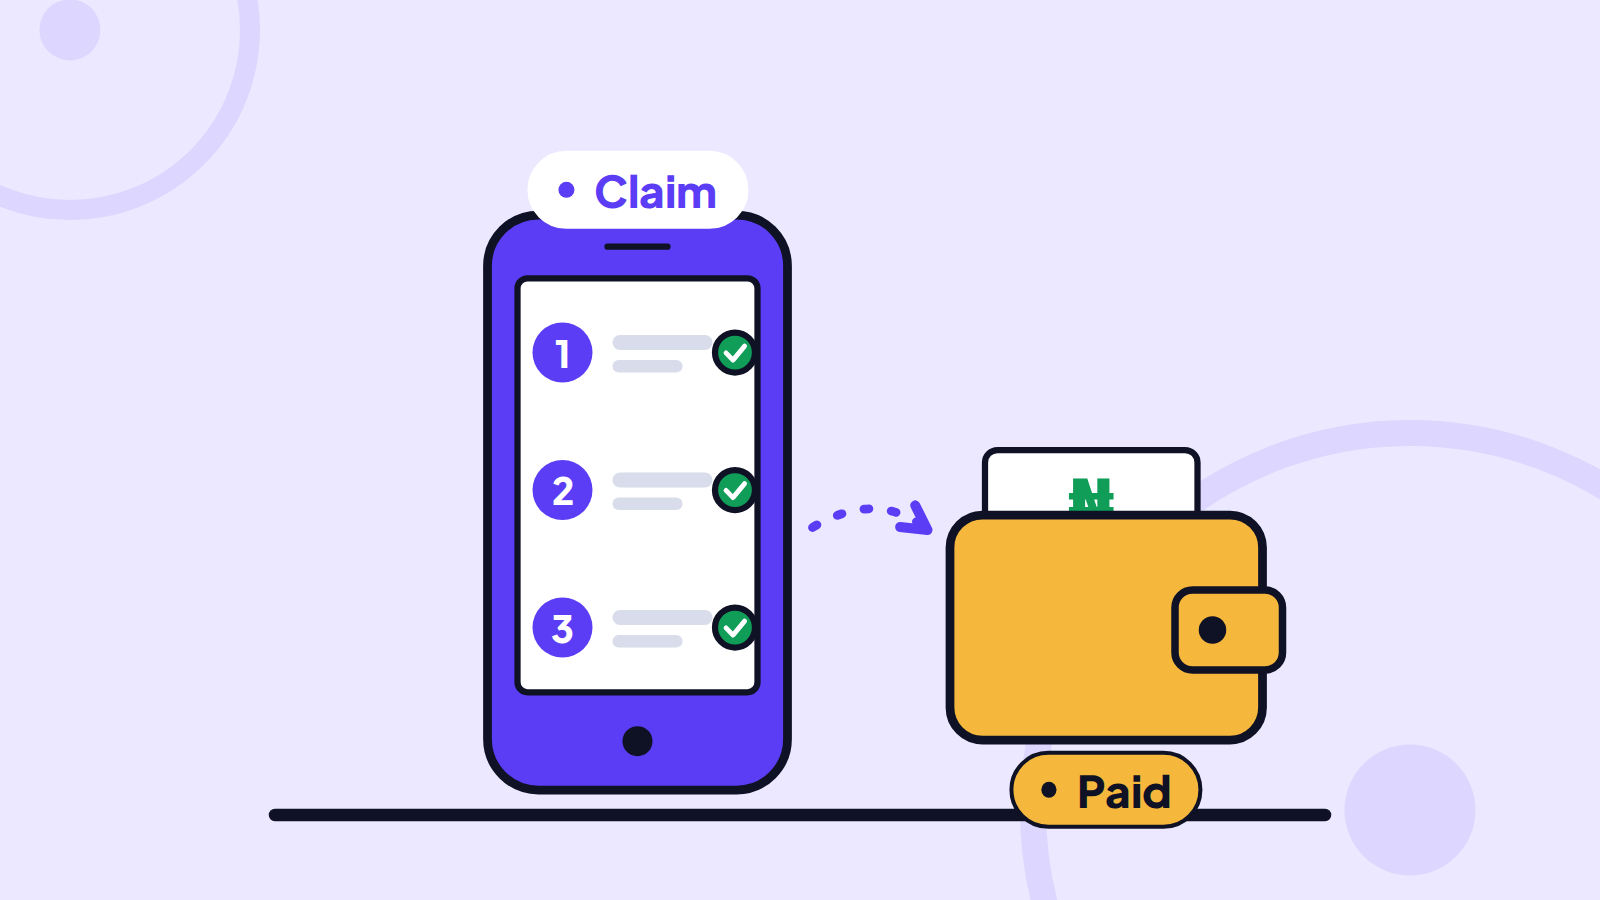
How to File an Insurance Claim in Nigeria: A Step-by-Step Guide
A clear, practical walkthrough of how to file an insurance claim in Nigeria, from the first phone call to getting paid, with the documents and timelines you need to know.
Flooding in Nigeria: How to Watch the Warnings, Prepare Your Home and Protect What You Own
Flooding is one of the most predictable disasters in Nigeria, yet it still catches households and small businesses off guard. Here is how to track the warnings, prepare your property and make sure your belongings are actually covered.
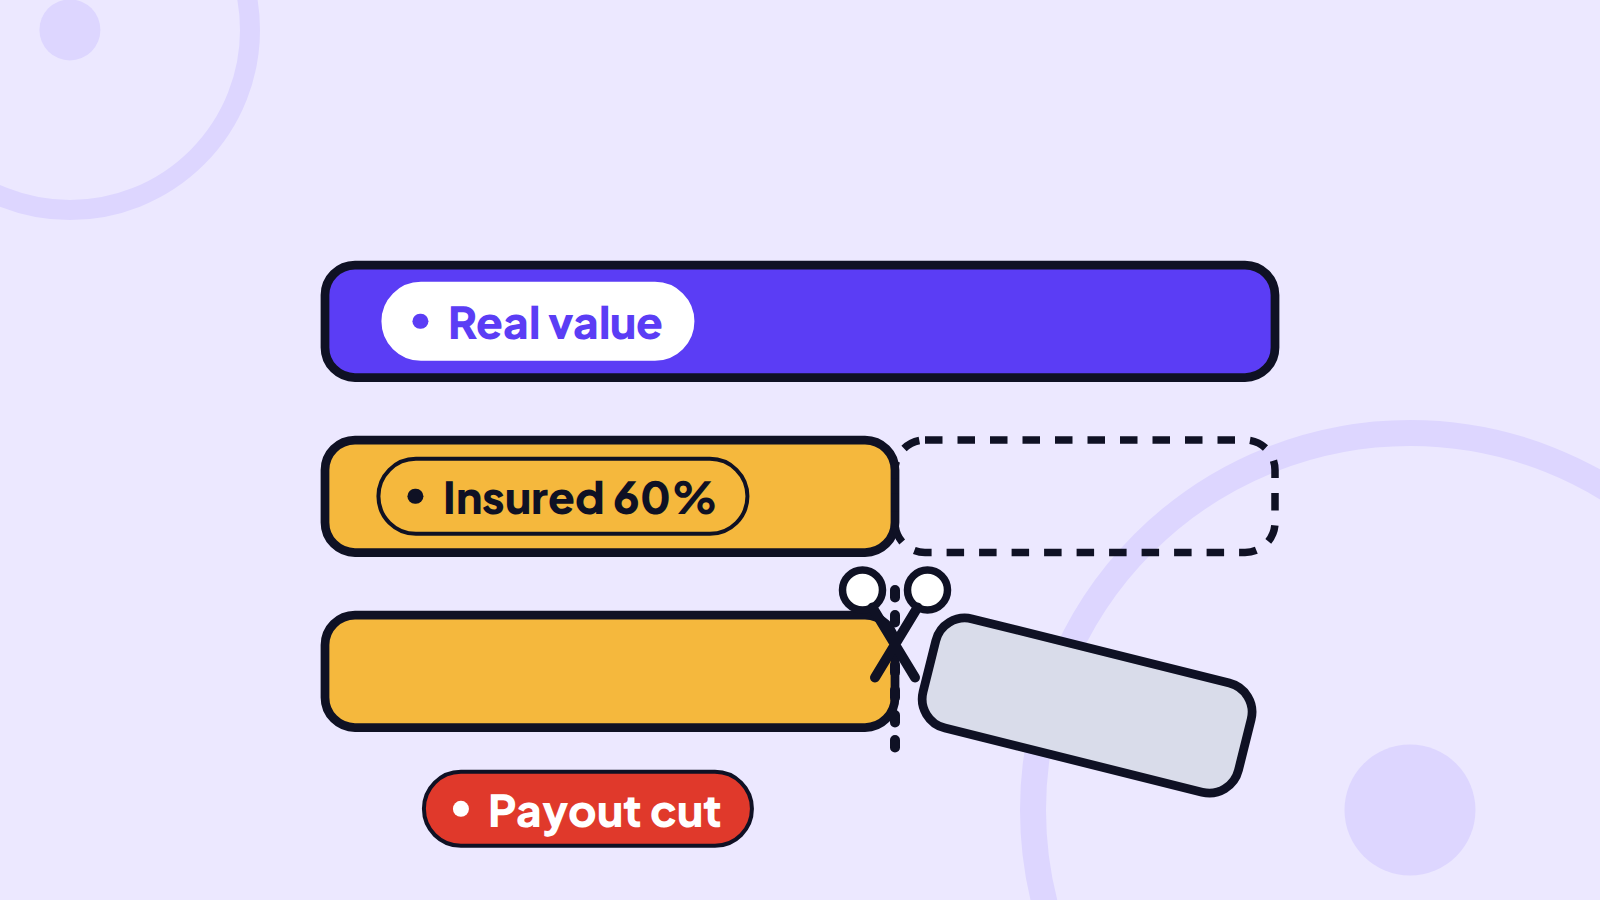
The Average Clause Explained: Why Underinsurance Cuts Your Payout
If you insure your property for less than its real replacement value, the average clause can reduce your claim payout by the same percentage you are underinsured. Here is how it works and how to avoid it.
How to Insure Your Generator in Nigeria
Generators are some of the most expensive things Nigerian homes and businesses own, yet they are rarely insured properly. Here is how to log, value and cover yours.
How to Value Your Assets for Insurance, and How Often to Update
Insure most things at replacement cost, use the right method for electronics, jewellery, vehicles, buildings and stock, and revalue at least yearly so your cover keeps up with prices.
Ready to protect what you own?
Log it, value it, and insure it in minutes. Just talk to Cova.
Start your vault free